
To file a VAT return in the UK, you submit the nine-box return to HMRC through MTD-compatible software and pay by the deadline, which is one calendar month and seven days after the VAT period ends. If you pay more than 15 days late, HMRC charges a 3% penalty, and interest runs from day one.
This guide is for large UK accounting practices that file VAT Return & Payments for lots of clients at once. It walks through the filing steps, payment methods, 2026 penalty rates and the errors that crop up most often, and it explains when outsourcing makes sense. Corientbs is a Coventry-based outsourcing partner to UK accountancy firms. It supports practices with VAT outsourcing and Making Tax Digital
What is a VAT Return, and Why Is It Important for UK Businesses?
A VAT return is the form a VAT-registered business submits to HMRC to report its sales, its purchases and the VAT it owes or can reclaim for a set period. Most UK businesses must file their VAT return every quarter unless they are under an annual or monthly scheme.
It must be understood that filing VAT returns and making payments is not just a box-ticking exercise for your clients. Through accurate VAT reporting, you can ensure for your clients:
- Regulatory compliance with HMRC rules
- Avoidance of penalties and interest
- Healthy cash flow management
These three figures show why VAT remains a high-volume compliance task for practices in 2026:
| Figure | What it shows | Source and date |
| £170.6bn | Total VAT receipts for April 2025 to February 2026, £9.2bn higher than the same period a year earlier. | HMRC tax receipts bulletin, 20 March 2026 |
| 2.79 million | VAT and/or PAYE-registered businesses in the UK in March 2026, up 1.9% in a year. | ONS, UK business: activity, size and location, 2026 |
| 7.75% | HMRC late payment interest on unpaid VAT from 9 January 2026 (Bank of England base rate 3.75% plus 4 percentage points). | HMRC (GOV.UK), published 19 December 2025 |
How Do You File a VAT Return Online, Step by Step?
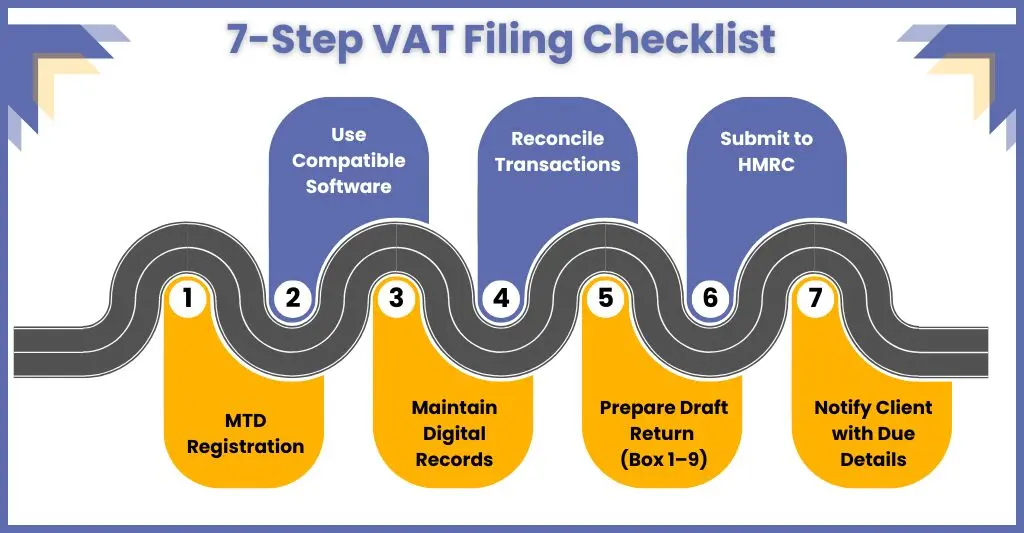
To file a VAT return online, confirm the client is on Making Tax Digital, prepare the nine-box return in MTD-compatible software and submit it to HMRC through that software. The seven steps below take a large practice from authorisation to audit trail.
Here’s a detailed guide to help you manage and file VAT returns online efficiently:
1. Ensure Your Client is MTD-Compliant
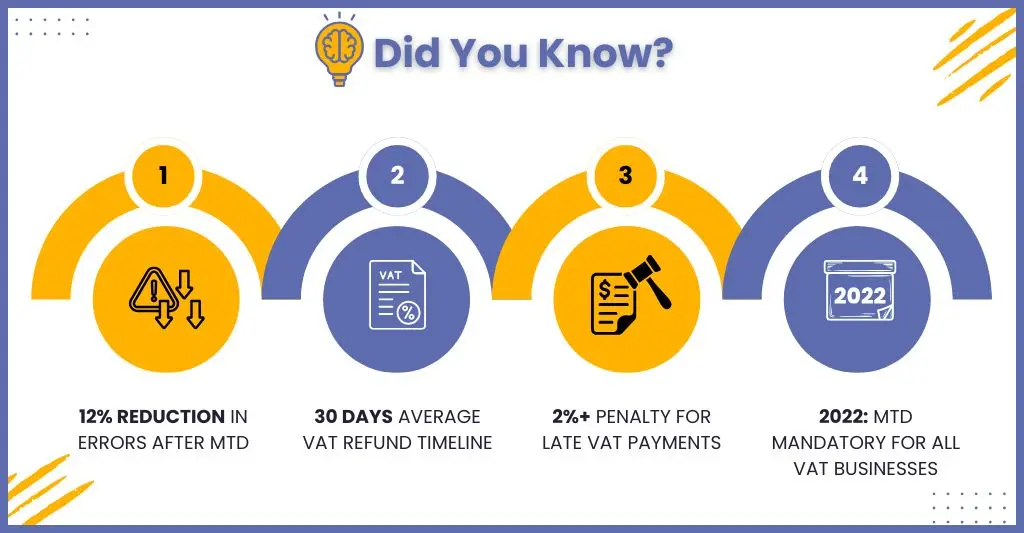
Before anything else, check that your client is registered for Making Tax Digital for VAT, which is compulsory for all VAT-registered businesses in the UK (regardless of turnover) since April 2022.
- Sign them up through the HMRC MTD VAT portal.
- Use their Government Gateway ID to link their profile with MTD services.
- Make sure you are registered as their agent and have the necessary authorisations via your Agent Services Account (ASA).
- For large portfolios, keep an authorisation register so no return is prepared before ASA access is confirmed.
2. Use MTD-Compatible Accounting Software
Select and set up an MTD-compliant accounting software that goes well with your practice workflow. Some of the popular options in accounting software are:
- Xero
- QuickBooks
- Sage
- FreeAgent
- IRIS
Clients who still work in spreadsheets can remain MTD-compliant if the spreadsheet is linked to HMRC through bridging software.
These tools are essential to manage your clients’ VAT, and they help in managing the following:
- Maintaining digital records of VAT-related transactions
- Enabling automated calculations of VAT owed or reclaimable
- Giving a direct link with HMRC for real-time submissions
You are responsible for ensuring that your accounting staff is trained in using these tools correctly and that all software updates are applied.
3. Maintain Digital Records and Reconcile Transactions
MTD for VAT requires digital records and digital links between systems.
Here are some of the records you will have to maintain digitally:
- Sales and purchase invoices
- VAT rates applied
- VAT account summary
- Dates of supply and payment
As an accounting practice, ensure each of your client’s data is:
- Digitally linked (no manual copying and pasting between systems)
- Reconciled with bank feeds and physical receipts
- Categorised correctly for standard-rated, zero-rated, or exempt VAT treatment
To avoid discrepancies in these records, it is recommended that a mid-period VAT health check be performed to resolve inconsistencies before submission deadlines.
4. Prepare the VAT Return
Once the VAT period ends (usually every quarter), use your accounting software to generate a draft return. The return has nine boxes:
| Box | What it shows |
| 1 | VAT due on sales and other outputs |
| 2 | VAT due on acquisitions of goods from EU member states into Northern Ireland |
| 3 | Total VAT due (Box 1 plus Box 2) |
| 4 | VAT reclaimed on purchases and other inputs |
| 5 | Net VAT to pay HMRC or reclaim (difference between Box 3 and Box 4) |
| 6 | Total value of sales and other outputs, excluding VAT |
| 7 | Total value of purchases and other inputs, excluding VAT |
| 8 | Total value of supplies of goods to EU member states (Northern Ireland) |
| 9 | Total value of acquisitions of goods from EU member states (Northern Ireland) |
Before submitting, verify every figure and run internal checks on:
- Non-standard VAT rates
- EU and non-EU sales and purchases
- Capital asset acquisitions
- Reverse charge mechanisms (common in construction or B2B digital services)
5. Submit the VAT Return to HMRC
Once reviewed and finalised, submit the VAT return to HMRC. To do that, use the MTD software, select the client and relevant VAT period, and submit the return directly to HMRC through the software. Once that is done, you will get a receipt and acknowledgement, which must be retained for audit.
6. Communicate VAT Liabilities and Payment Instructions to the Client
Once you have filed a VAT return, you must inform your client of the VAT amount and its due date, which is one calendar month and seven days after the VAT period ends. Hence, provide the following information to your clients:
- The amount payable
- Due date
- Payment reference (usually the VAT registration number)
- Recommended payment methods
7. Keep a Digital Audit Trail
For every VAT return filed, maintain a clear audit trail including:
- Source documents (invoices, receipts)
- VAT return report and breakdown
- Client authorisation (if required)
- Submission confirmation from HMRC
Keeping these records will protect your practice and your Client during VAT inspections or if amendments are required. HMRC expects VAT records to be kept for six years.
How Do You Pay Your VAT Bill to HMRC Online?
Pay your VAT bill electronically so cleared funds reach HMRC by the deadline: one calendar month and seven days after the VAT period ends. Use the client’s VAT registration number as the payment reference. Pick the method by how quickly the money must arrive.
| Payment method | How it works for a practice |
| Direct Debit | Set up before the return is submitted. HMRC then collects the amount automatically, which removes the risk of a missed payment. |
| Faster Payments (online or telephone banking) | Usually the quickest option for a last-minute payment. Submit well before the deadline and check that funds have cleared. |
| Bacs | Takes up to three working days, so schedule it early. |
| CHAPS | Same-day transfer for large or urgent payments, subject to the bank’s cut-off time. |
| Debit or corporate credit card online | Check HMRC’s current card rules and any fee first. Personal credit cards are not accepted. |
| Payment link in accounting software | Pays directly from the software where the provider supports it. Keep the confirmation with the audit trail. |
What Are the Penalties for Filing or Paying VAT Late in 2026?
HMRC replaced the VAT default surcharge on 1 January 2023 with two separate penalties: points for late returns and percentage charges for late payment, plus interest. A quarterly filer pays £200 once they reach four penalty points. Late payment costs 3% of the unpaid VAT at day 15, and a further 3% at day 30.
Late submission: points and thresholds
| Return frequency | Points threshold | Penalty at the threshold |
| Annual | 2 points | £200, then £200 for each further late return |
| Quarterly | 4 points | £200, then £200 for each further late return |
| Monthly | 5 points | £200, then £200 for each further late return |
Source: HMRC, Penalties for late submission (GOV.UK)
Late payment: penalties and interest
| Days overdue | What HMRC charges |
| 1 to 15 days | No late payment penalty. Interest still runs from day one. |
| 16 to 30 days | First penalty: 3% of the VAT still unpaid at day 15. |
| 31 days or more | First penalty rises by a further 3% of the VAT unpaid at day 30. A second penalty accrues daily at 10% a year on the unpaid VAT. |
| Interest (all periods) | Bank of England base rate plus 4 percentage points, which is 7.75% from 9 January 2026. |
Sources: HMRC, How late payment penalties work (GOV.UK) and HMRC interest rates notice, 19 December 2025.
Worked example from HMRC: if £15,000 of VAT is still unpaid at day 30, the first late payment penalty is £900, made up of 3% of £15,000 at day 15 and a further 3% at day 30.
A payment plan can stop penalties building. HMRC does not charge a late payment penalty if the business proposes a payment plan within 15 days of the due date, HMRC agrees it and the business keeps to its terms. Details: HMRC press release on VAT penalties.
What Are the Most Common Mistakes When Filing and Paying VAT?
The most common VAT mistakes are missed deadlines, wrong VAT codes, non-digital records, the wrong VAT scheme, cross-border errors, and late client notification. Each is avoidable with a controlled, repeatable process.
Missing Filing and Payment Deadlines
Failure to submit payments or meet the VAT returns deadline (usually 1 calendar month and 7 days after the end of the VAT period) can lead to:
- Late submission points and late payment penalties of 3% (see the penalty tables above)
- Accrued interest on unpaid VAT
- Reputational damage with clients
Solution:
Work on implementing automated reminders using your practice management software. Also, keep a master VAT calendar that flags deadlines per Client and VAT scheme (quarterly, monthly, or annual).
Incorrect VAT Calculations
Miscalculations in VAT are a common occurrence that occurs due to misconfigured accounting software or manual calculations; this can result in:
- Overstated VAT liabilities
- Under-claimed input VAT
- Misclassification of exempt or zero-rated goods
Solution:
To avoid miscalculations, you are required to correctly set the VAT codes in your MTD-compatible software. Also, prioritise regularly reconciling input/output VAT against sales and purchase ledgers and conducting internal peer reviews before submission.
Using Incomplete or Non-Digital Records
As per the MTD regulations, all VAT data must be recorded in digital format. Manual re-keying and broken digital links, not spreadsheets themselves, are what breach the rules.
Solution:
Make a point to use MTD-approved software with live bank feeds. Also, educate your clients on the importance of timely submission of their records in digital format. We recommend investing in secure data storage infrastructure for the safe transfer of client data.
Applying the Wrong VAT Scheme
Applying the wrong VAT scheme is a mistake that keeps coming up, and failing to correct it when your client’s turnover changes leads to underpayments or overpayments.
Solution:
To avoid such a mistake, you must conduct quarterly reviews of your client’s turnover and business activities to assess VAT scheme suitability. You can also seek help from a VAT specialist, who you can access through VAT outsourcing services offered by service providers.
Failure to Handle International Transactions Correctly
Recently, we have encountered accounting practices that commit mistakes when handling EU and non-EU transactions. These mistakes include:
- Not applying reverse charge correctly
- Misreporting import VAT
- Confusion between dispatches and exports
Solution:
Keep up with the UK-EU VAT rules and make sure your team is trained in how cross-border transactions are treated. It also helps to use accounting software that flags anything unusual in how foreign VAT is handled.
Not telling clients what they owe
Sometimes a practice submits the return but is slow to tell the client how much they need to pay, and the payment deadline slips by.
Solution:
Create a system to auto-generate VAT summaries and payment instructions post-submission. Notify clients the same day the return is filed and offer payment support if required.
What Are the Benefits of Filing VAT Returns Online and Automating Your Process?
Filing online and automating the process cuts manual-entry errors, saves time and strengthens your audit trails. It also lets a practice take on more VAT work without adding headcount. And since April 2022, MTD has been a compliance requirement for every VAT-registered business, so automation is no longer a choice.
Better accuracy, fewer errors
We all know how many mistakes creep in with manual data entry: miskeyed invoices, wrong VAT rates, duplicated entries. MTD-compliant accounting software has largely put an end to those. With it, you can:
- Automatically pull VAT data from digital records
- Calculate VAT liabilities without manual intervention
- Flag anomalies or inconsistencies in real-time
Saving time for you and your clients
Filing VAT the old way took ages, especially with paper invoices, spreadsheet reconciliations and endless chasing of clients for missing information. Automate the whole process and you can:
- Generate returns in minutes, not hours
- Eliminate repetitive admin tasks
- Batch-file VAT returns for multiple clients from a central dashboard
This efficiency frees your team to focus on higher-value advisory work, from tax planning to cash flow strategy.
Guaranteed HMRC Compliance
Using MTD-approved software ensures your submissions align with HMRC requirements. You’ll never worry about:
Following HMRC compliance requirements is important, but also complex, and chances are that you can miss out on some. But by using MTD-compliant software, you can ensure submissions are done as per the HMRC mandate. Incorporate this tool either by buying it or accessing it through accounting outsourcing services.
Real-Time Visibility and Better Decision-Making
By automating VAT solutions, you can add value to your clients by giving them instant access in real time. These real-time insights give you the following:
- Accurate cash flow forecasts
- Timely reminders of payment due dates
- Early identification of VAT liabilities and reclaim opportunities
Such real-time insights enhance client confidence and position your practice as a proactive financial partner.
Scaling up as your client list grows
Growing a VAT service by hand just doesn’t work. Automating or filing returns online lets you scale without much effort. Whether you’re handling VAT for 5 clients or 500, automation helps you manage it without growing your team.
With automation, you can:
- Onboard new clients quickly
- Handle complex VAT scenarios (e.g. partial exemption, imports and exports)
- Centralise submissions and client reporting
Corient’s AI Crew supports this: Corby handles reconciliation, and Sherlock detects errors before returns are submitted.
Stronger audit trails and lower risk
One of the biggest advantages of digital systems is how transparent they are. In accounting software, every action is timestamped and traceable, from the moment an invoice is uploaded through to the final submission.
That trail really earns its keep if HMRC ever opens an enquiry. You can hand over a clear record of the transactions, the supporting documents, the proof of submission and the payment records. Having all of that to hand cuts the risk of penalties, and over time it makes your compliance a lot harder to knock off course.
When Should a Large Practice Outsource VAT Work to Experts?
A large practice should outsource VAT when portfolio volume, sector complexity or seasonal peaks outgrow in-house capacity. A specialist partner adds technical cover and flexible capacity without extra hiring. Software automates the basics, but it cannot replace VAT judgement.
| Factor | In-house VAT team | Outsourced VAT partner (typical) |
| Capacity at deadline peaks | Fixed headcount | Scales with workload |
| Technical updates | Team tracks HMRC changes itself | Partner tracks and applies changes |
| Complex sectors | Depends on individual experience | Specialist cover on request |
| Cost model | Salaries, training and software | Pay for the work required |
That’s where VAT specialists come in, and an accounting outsourcing provider is one of the easiest places to find experienced ones. If your practice is looking after a growing client portfolio, bringing in dedicated VAT professionals gives you extra assurance and efficiency, and it adds real value for your clients too.
Handle complex VAT scenarios with confidence
UK VAT is rarely straightforward, and dealing with the tricky cases takes more than good data entry. You need someone who can interpret the rules, use sound judgment and keep their technical knowledge current, and that’s what dedicated VAT specialists bring.
A VAT expert helps your team confidently manage:
- Retail and hospitality-specific VAT rules
- Construction Industry Scheme (CIS) reverse charges
- International eCommerce VAT obligations
- Charity and not-for-profit exemptions
Minimise risk and avoid costly penalties
Mistakes in VAT returns happen, so don’t assume yours won’t. A transaction gets misclassified, a figure is reported wrongly, a submission goes in late, and suddenly you’re looking at penalties, interest charges and possibly a full VAT inspection.
This is where VAT specialists earn their fee. They check work before it goes out, review reconciliations and know what HMRC looks for, so your clients stay compliant and ready if an audit ever lands.
Work faster without losing accuracy
Time is money, and few people know that better than a practice juggling VAT for lots of clients at once. It’s easy to get bogged down chasing VAT anomalies or digging into sector-specific rules, and that’s exactly the kind of work VAT specialists can handle quickly. It frees your in-house team to spend their time on client relationships and advisory work, while the VAT compliance stays at the same high standard.
Stay ahead of changing VAT rules
HMRC updates and VAT obligations for digital platforms change all the time. With specialists on your side, your firm stays informed and prepared without someone in-house having to track every legislative update.
Give clients more reason to stay
Bringing in experts moves your practice from purely transactional work towards something more valuable. Clients notice that. It builds their confidence in you, helps you keep them for the long term and sets you apart from other practices.
Frequently Asked Questions (FAQ)
1. How often do I need to file a VAT return in the UK?
Most VAT-registered businesses file every quarter, so that’s four returns a year. Some go monthly, usually because they’re owed repayments and want them sooner. Others use the Annual Accounting Scheme: one return a year, with interim payments along the way. Whichever route a client is on, the return and the payment fall due at the same time, one calendar month and seven days after the period ends.
2. What happens if I file my VAT return late?
Every late return earns a penalty point. Once a quarterly filer hits four points, HMRC charges £200, and it charges another £200 for each late return after that while they’re still at the threshold. The old default surcharge is gone for periods starting on or after 1 January 2023. Paying late is a separate matter, and that penalty starts at 3% on day 15.
3. How long does HMRC have to pay VAT refund?
HMRC usually repays VAT within 30 days of receiving the return. If nothing has arrived after 30 days, contact HMRC. The repayment goes directly to the bank account HMRC holds for the business, so confirm those details are current before you file. Repayment returns can attract extra checks, which may add time.
4. Does HMRC check all VAT returns?
Not by hand, no. HMRC does risk-screen submissions, though, and it can open a compliance check on any return it chooses. The usual triggers are unusual repayment claims, VAT codes that don’t match up and missing records. Keep a digital audit trail of invoices, reconciliations and the submission receipt, and your practice can answer an enquiry quickly and cut the risk of penalties.
5. What is the deadline to pay VAT to HMRC?
VAT is due one calendar month and seven days after the end of the VAT period, the same date as the return deadline. Cleared funds must reach HMRC by then, so allow for Bacs taking up to three working days. If the payment is more than 15 days overdue, HMRC charges a 3% penalty on the unpaid VAT.
6. Can an accounting practice file VAT returns for clients under MTD?
Yes. The practice needs an Agent Services Account, the client’s authorisation and MTD-compatible software to submit returns on their behalf. Many large practices add bridging software where clients still keep spreadsheets. Corient’s VAT outsourcing team can prepare and submit returns for a practice, so partners keep the client relationship while the compliance workload is covered.
Conclusion
Filing and paying your VAT return & payment online seems overwhelming, but that’s not the case. With the right tools, knowledge, and expert support, you can stay compliant, avoid penalties, and focus on growing your practice. Whether you are integrating online filing of VAT returns or embracing automation, both are important in qualifying into a modern UK accounting practice.
Where will you find such expertise, especially when you are saddled with multiple VAT responsibilities? Here, we are introducing accounting outsourcing services like Corientbs, which are valuable when offering VAT specialists through their VAT outsourcing services.
Corientbs has made its name by providing tech-savvy and compliant VAT services that have made a difference for multiple practices in the UK market. Apart from that, it also offers bookkeeping, payroll, and year-end services, to name a few. To learn more about our services or to clarify your doubts, write down your questions on our website contact form, and our executive will connect with you soon.
Best of luck in your future VAT endeavours, and looking forward to hearing from you soon.
