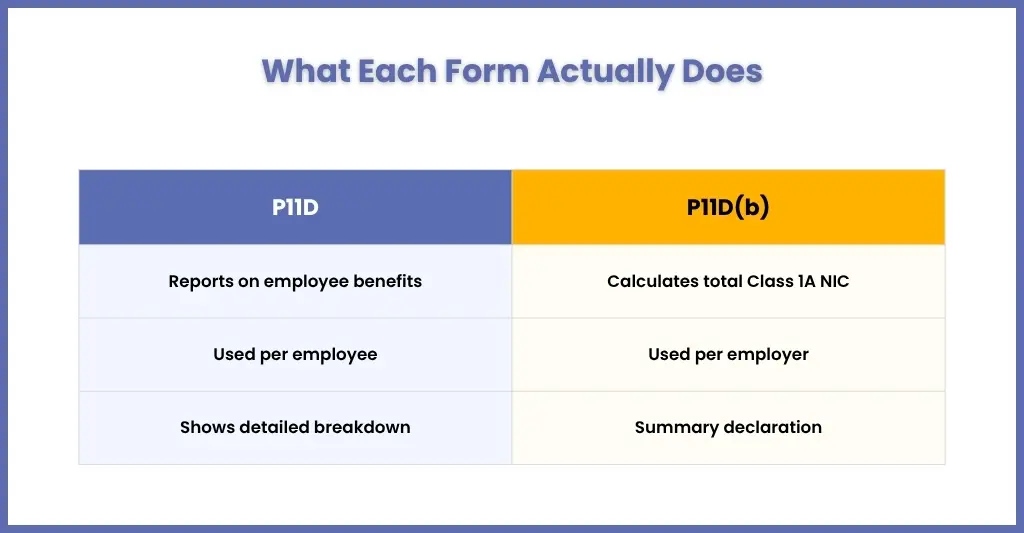
P11D reports each employee’s taxable benefits and expenses to HMRC and the employee, one form per person. P11D(b) is the single employer return declaring the total Class 1A National Insurance (15% for 2026/27) due on those benefits. Both are due by 6 July after the tax year; Class 1A is paid by 22 July.
Here’s a simple way to understand P11D vs P11D(b).
- P11D reports employee benefits and expenses
- P11D(b) reports the total Class 1A National Insurance due on those benefits
But here is where things get confusing for both accounting practices and employers. Let’s explain this situation through a scenario.
An expanding consultancy firm in the UK has been providing company cars, medical insurance and travel reimbursements to its employees. At the year-end, their accounting team submitted P11D forms but completely forgot about P11D(b).
A few weeks later, HMRC issued a penalty notice. The issue wasn’t negligence. There was confusion around P11D vs P11D(b), something that even experienced teams get wrong under pressure. Scarily, these days, even accounting practices are facing the same issue while handling the payroll of their clients.
If you’re managing payroll for multiple clients, then it’s important to negate this compliance risk once and for all.
In this guide, we’ll break down:
- What P11D and P11D(b) actually mean
- Key differences
- 2026 deadlines you cannot miss
- Penalties to avoid
- And how outsourcing can manage this efficiently
2026 update: the 2025/26 deadline (6 July 2026) has passed. If a client has not filed, file now and see the penalties section. The next deadline for 2026/27 benefits is 6 July 2027, with Class 1A due by 22 July 2027 (19 July for cheques). Budget 2026 (28 October 2026) did not move these dates: the 2026/27 tax year is still reported on P11D and P11D(b) in July 2027, even though mandatory payrolling starts on 6 April 2027 (see “Looking ahead” below).
What Is a P11D Form?
A P11D is the form an employer files with HMRC and provides to the employee to report taxable benefits in kind and expenses that were not payrolled. It is filed once for each employee or director who received them.
P11D forms are used in reporting benefits in kind and expenses provided by your clients to their employees.
The benefits include:
- Company cars and fuel
- Private medical insurance
- Interest-free or low-interest loans
- Living accommodation
- Certain reimbursed expenses
If a benefit is not included in the payroll, then it must be reported on a P11D. These P11D forms are required by your client employers to submit for each employee who gets tax benefits. Employers must also give each employee a copy by 6 July.
What Is a P11D (b) Form and How Is It Different from P11D?
A P11D(b) is the employer’s annual return declaring the total Class 1A National Insurance due on employee benefits. It is filed once per employer, not per employee, and is sent only to HMRC.
Many practices, employers, and employees get confused between P11D and P11D (b). One thing you need to understand is that P11D(b) is the form that your client’s employer must fill out, and it calculates the total Class 1A National Insurance due on all employee benefits. In short, it summarises the information from all P11D forms submitted by their employees.
Unlike P11D, P11D (b) has to be submitted only by the employer, meaning one P11D (b) per employer. It acts as a declaration that all P11Ds are complete and accurate.
P11D vs P11D(b) — Side-by-Side Comparison: What Is the Difference?
The difference is scope: a P11D lists one person’s benefits, while a P11D(b) totals the employer’s Class 1A liability. The table compares them.
| Aspect | P11D | P11D(b) |
| Purpose | Reports individual employee benefits | Calculates employers’ NI contributions |
| Frequency | One per employee | One per employer |
| Content | Detailed benefit breakdown provided to an employee | Summary calculations |
| Recipients | HMRC and the employee | HMRC only |
| Deadline | 6 July 2026 (passed); next 6 July 2027 (2026/27 benefits) | 6 July 2026 (passed); next 6 July 2027 (2026/27 benefits) |
| Payrolled benefits | Not included | Still needed for 2025/26 and 2026/27 to declare Class 1A. From 6 April 2027, Class 1A on payrolled benefits is reported and paid through payroll, so P11D(b) covers only non-payrolled benefits |
| Late penalty | Up to £300 per form, then up to £60 a day | £100 per 50 employees per month |
The first one focuses on employee expenses and benefits, and the second one deals with your client’s employers’ National Insurance obligations. Both work together in the compliance process.
2026 Deadlines You Cannot Afford to Miss: When Are the P11D and P11D(b) Deadlines?
The 2025/26 deadline for both forms was 6 July 2026 and has passed. The next is 6 July 2027, for tax year 2026/27. Class 1A is due by 22 July electronically or 19 July by cheque, per HMRC.
| What you must do | 2025/26 (passed) | 2026/27 (next) |
| Report benefits (P11D) and Class 1A (P11D(b)) | 6 July 2026 | 6 July 2027 |
| Pay Class 1A | 22 July 2026 (19 July by cheque) | 22 July 2027 (19 July by cheque) |
| PAYE Settlement Agreement tax and Class 1B | 22 October 2026 (19 October by cheque) | 22 October 2027 (19 October by cheque) |
Another point at which many practices get confused is the deadlines associated with P11D and P11D(b).
Let’s end this confusion at once:
- Both forms have to be submitted by 6 July and have to be sent electronically through approved software.
With regard to payment of Class 1A National Insurance, it has different deadlines:
- Electronic payments: 22 July
- Postal payments: 19 July
Missing out on any of the above-mentioned payment deadlines will attract serious penalties and interest from HMRC.
Looking ahead: Budget 2026 (28 October 2026) kept the phased timetable HMRC confirmed in June 2026. Mandatory payrolling starts on 6 April 2027 for company cars, car fuel, vans, van fuel and employer-provided medical benefits, and on 6 April 2028 for most other benefits. Employment-related loans and living accommodation are excluded and stay voluntary. P11D(b) and Class 1A still apply to non-payrolled benefits, and 2026/27 benefits are still reported under the current rules in July 2027. Sources: HMRC Employer Bulletin, October 2026, HMRC phased-introduction guidance and Budget 2026 in full (GOV.UK).
| From | What is covered | How it is reported |
| 6 April 2027 (Phase 1) | Company cars, car fuel, vans, van fuel and employer-provided medical benefits | Income Tax and Class 1A reported and paid through payroll in real time |
| 6 April 2028 (Phase 2) | Most other benefits | Real-time payrolling; any benefits not mandated are still reported on P11D and P11D(b) |
| Excluded | Employment-related loans and living accommodation (voluntary) | P11D and P11D(b), unless the employer chooses to payroll them |
| Exception | Eligible globally mobile employees, where the employer opts in via HMRC’s G-Form (from November 2026) | Left out of mandatory payrolling; reported on P11D and P11D(b) |
Budget 2026 also confirmed that the government will legislate so that an employer’s payment of the Immigration Skills Charge or a Certificate of Sponsorship fee is not a taxable benefit, for payments made on or after 28 October 2026 (Lewis Silkin).
P11D Penalties – What Happens If You File Late or Incorrectly?
HMRC charges up to £300 per late P11D plus up to £60 a day, and £100 per 50 employees for each month a P11D(b) is late. HMRC’s manual caps P11D(b) penalties at 12 months and at the Class 1A due.
HMRC applies penalties for late submissions of P11D. As per Section 98(1)(b) Taxes Management Act 1970:
- Maximum initial penalty of £300 per form for failure to submit forms P11D
- Continuing penalties of a maximum of £60 per day thereafter, until the failure has been remedied.
Similarly, penalties for the late submission of P11D(b) are:
- £100 per 50 employees for each month
Penalties will also apply if:
- Benefits are underreported
- Forms contain errors
- Class 1A NIC is miscalculated
While managing multiple clients, even small errors across several submissions can quickly become costly and time-consuming. Due to this, many practices have sought assistance through payroll outsourcing services to reduce submission errors and speed up the entire process.
How to Submit P11D and P11D(b) to HMRC — Step by Step
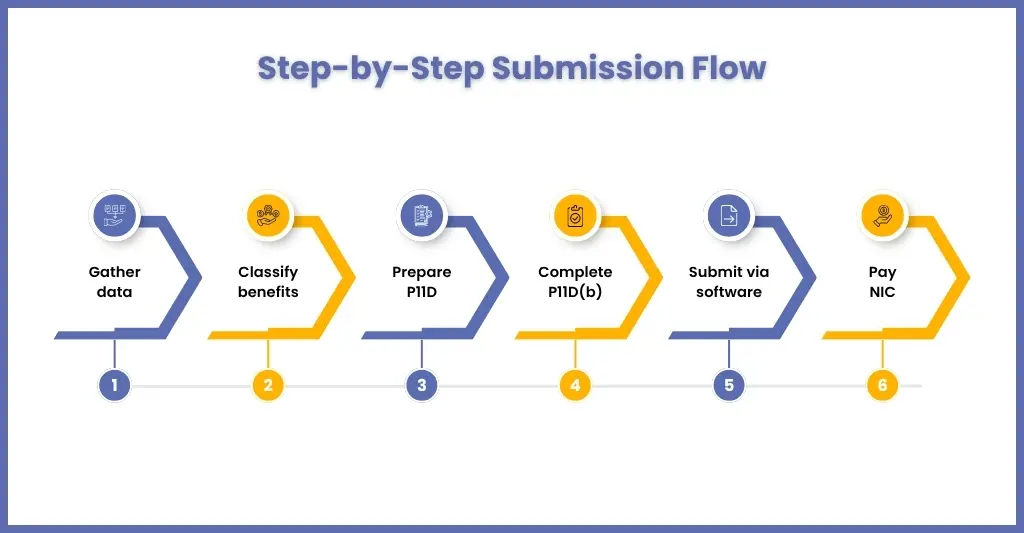
File both forms online through HMRC PAYE Online or HMRC-recognised payroll software by 6 July, then pay Class 1A by 22 July. The steps are: gather data, classify benefits, prepare P11Ds, complete the P11D(b), submit, and pay.
Submitting P11D and P11D(b) requires precision, and most errors happen not because you are unaware of the rules but due to rushed data and last-minute submissions.
Let’s break this down in a way that helps you get it right the first time.
Step 1: Gather Benefits Data
Here’s where it begins, including the mistakes. You will have to collect all the data accurately for the entire tax year (6 April to 5 April).
What data do you need to gather?
- Employee benefits in kind (BIKs)
- Reimbursed expenses
- Payroll records (to identify payroll benefits)
- Company car details (CO₂ emissions, fuel type, availability)
- Private medical insurance values
- Loans or advances provided to employees
- Expense claims and supporting receipts
Step 2: Classify Benefits Correctly
After collecting the data, it must be classified properly, which can be challenging and chances of error occuring.
Classify the benefits as follows:
- Taxable benefits: Must be reported
- Exempt benefits: No reporting required
- Payroll benefits: Already taxed via payroll
Examples:
- Company car: Taxable (report in P11D if not payrolled)
- Private medical insurance: Taxable
- Business travel reimbursements: Often exempt
- Trivial benefits: Usually exempt
For successful classification, maintain a benefit classification guide and cross-check payroll vs non-payroll items. Also, keep an eye on the HMRC guidance annually for any updates. Incorrect classification is one of the biggest reasons for HMRC penalties.
Step 3: Preparing P11D Forms
Start preparing P11D forms for each employee.
Each form must include:
- Employee details (name, NI number, payroll ID)
- Breakdown of benefits received
- Cash equivalent value of each benefit
Get a payroll software to automate the entire process and conduct a thorough review of the forms before submission.
Step 4: Complete P11D(b)
P11D(b) is not just a form; it’s a declaration.
It confirms that:
- All P11Ds are complete and accurate
- Declare total benefits provided
- Calculate total Class 1A NIC liability
It was never P11D vs P11D(b), P11D is the detail, P11D(b) is the financial impact.
Step 5: Submit via HMRC Compatible Software
Once the P11Ds and P11D(b)s are prepared, it’s time to submit them, and it must be done using payroll/accounting software.
The benefit of using the best payroll software is:
- It automates calculations and reduces errors
- Ideal for practices that handle multiple clients
Submit the forms before 6 July, and don’t wait until the deadline passes; chances are, the HMRC system will get overloaded.
Step 6: Pay Class 1A NIC
With submission done, now it’s time for payment.
Make note of these key deadlines:
- 19 July for postal payments
- 22 July for electronic payments
Missing out on these deadlines leads to interest and penalties.
From 6 April 2027, Class 1A on payrolled benefits is reported and paid through payroll in real time, so for 2027/28 onwards the annual 22 July payment will cover only benefits that are not payrolled. The 22 July 2027 payment still covers all 2026/27 benefits, so employers face a one-off overlap that year (HMRC Employer Bulletin).
How Does Corientbs Help UK Accounting Practices Manage P11D and P11D(b) Submissions?
Corientbs, based in Coventry, helps UK accounting practices by taking on end-to-end P11D and P11D(b) preparation and submission through its payroll outsourcing service, so large practices can scale benefits reporting at peak season.
When it was one client, it was fine, but when you started handling P11D and P11D(b) submissions for multiple clients, things started getting out of hand. During the peak season, you must have faced:
- Workload spikes
- Tight deadlines
- Compliance pressure
- Risk of errors
This is where payroll outsourcing comes as a blessing in disguise, and here’s where Corientbs comes into the picture.
We support UK accounting practices by managing end-to-end P11D and P11D(b) processes.
Through our payroll outsourcing services, we handle:
- Data collection and validation
- Benefit classification
- Accurate form preparation
- Timely submission
- NIC calculation and reporting
Our offshoring services add scalable capacity for peak periods, our tax outsourcing support covers wider compliance work, and our AI Crew tool Sherlock flags data errors before forms reach HMRC.
Through our services, you will avoid:
- Compliance risk
- Last-minute rush
- And provide more time towards:
- High-value advisory work
- Scalable services during peak seasons
Frequently Asked Questions About P11D vs P11D(b)
Do I need to submit both P11D and P11D(b)?
Usually, yes. If a client provides taxable benefits or expenses that are not payrolled, it files a P11D for each recipient and one P11D(b) declaring Class 1A National Insurance. If every benefit was payrolled, only the P11D(b) is needed. Where no Class 1A is due, the employer can file a “no return of Class 1A” declaration instead.
What is the penalty for filing a P11D(b) late?
HMRC charges £100 per 50 employees for each month or part month a P11D(b) is late. A client with 120 employees therefore pays £300 a month, because 120 counts as three bands of 50. HMRC’s manual caps these penalties at 12 months and at the Class 1A due. Late Class 1A payments also attract interest.
What is the difference between P11D and P11D(b) for payrolled benefits?
A P11D never includes benefits already taxed through payroll. For 2025/26 and 2026/27 the P11D(b) still declares and pays Class 1A on those payrolled benefits. From 6 April 2027, Class 1A on payrolled benefits is reported and paid through payroll, so the P11D(b) covers only non-payrolled benefits.
What are the P11D and P11D(b) deadlines?
For 2025/26 the P11D and P11D(b) deadline was 6 July 2026, with Class 1A due by 22 July 2026 electronically or 19 July by cheque. The next deadline is 6 July 2027, covering the 2026/27 tax year, with the same payment dates. Employees must also receive their P11D copy by 6 July.
Is P11D being phased out?
Not yet, but its scope is shrinking. Budget 2026 kept the confirmed schedule: mandatory payrolling from 6 April 2027 for company cars, car fuel, vans, van fuel and medical benefits, and from 6 April 2028 for most other benefits. Loans and living accommodation are excluded. P11D and P11D(b) still apply to non-payrolled benefits.
What is the Class 1A National Insurance rate for 2026/27?
The Class 1A rate on expenses and benefits is 15% for 2026/27, the same as 2025/26. It is an employer-only charge, with no employee National Insurance deduction. For example, £100,000 of taxable benefits declared on a P11D(b) creates £15,000 of Class 1A National Insurance, payable by 22 July after the tax year ends.
What if a client missed the 6 July 2026 deadline?
File the outstanding P11Ds and P11D(b) immediately, because penalties build every month and for every form. Pay any Class 1A due, as interest runs on late payment. Then review any HMRC penalty notice and appeal if there is a reasonable excuse. Practices should also tighten year-end data cut-offs so the delay does not recur next July.
Which benefits and employees are excluded from mandatory payrolling?
Employment-related loans and living accommodation sit outside mandatory payrolling and stay voluntary, so they continue on P11D and P11D(b). Employers can also voluntarily except eligible globally mobile employees from 6 April 2027 using HMRC’s G-Form, available from November 2026, and keep reporting their benefits through P11D and P11D(b).
Conclusion
It’s important to have a deep understanding of P11D vs P11D(b). Yes, both are different from each other, but both need the same ingredients.
- Accurate data
- Correct classification
- Strict deadlines
- Compliance with HMRC regulations
With increasing reporting complexity, growing client demands, and high volumes, many practices are moving toward outsourced support for efficiency, speed, and scalability.
By partnering with experts like Corientbs, you can reduce your:
- Compliance risk
- Improve accuracy
- Handle peak workloads efficiently
- Focus on higher-value services
Avoid firefighting this P11D season by filling out our contact form and staying ahead of deadlines.