National Insurance Contributions (NICs) are a UK tax on earnings and self-employed profits that funds the State Pension and certain benefits. In 2026–27, employees pay 8% on earnings between £12,570 and £50,270 and 2% above that, while employers pay 15% on earnings above £5,000 per employee.
National Insurance Contributions (NICs) are a significant part of the UK tax system; after all, they are the UK’s second-largest tax. HMRC’s annual receipts bulletin, released on 21 August 2026, shows that Income Tax, Capital Gains Tax and NICs together made up 59% of the £937.8 billion HMRC collected in 2025 to 2026. Employees and self-employed individuals pay it on their earnings, and employers pay it on the earnings of those they employ. Unlike income tax, NICs are not charged on income from other sources such as savings, pensions or property.
In the 2026–27 tax year, the headline rates have not moved, but the Class 2 and Class 3 rates, the Lower Earnings Limit and the rules on voluntary contributions from abroad have all changed. In this blog, we’ll break down the different NIC classes, explain how to manage contributions and outline what accounting professionals should know, particularly larger practices running high payroll volumes.
What Are Class 1 National Insurance Contributions?
Class 1 National Insurance Contributions (NICs) apply to employees and employers on earnings from employment. The PAYE system automatically subtracts these contributions from wages based on an employee’s salary. In 2026–27, employees pay 8% on earnings between £12,570 and £50,270 and 2% above that. Employers pay 15% on earnings above £5,000 a year.
Who Pays Class 1 NICs?
The responsibility of paying Class 1 National Insurance is with the following:
- Employee NICs: Paid on earnings above the Primary Threshold (£242 a week, or £12,570 a year).
- Employer NICs: Paid on earnings above the Secondary Threshold (£96 a week, or £5,000 a year).
Specific key points to remember:
- Typically affects employees aged 16 to State Pension age.
- The National Insurance Rates vary depending on earnings limit and NIC thresholds.
- Eligible employers can claim the Employment Allowance, which takes up to £10,500 off the annual employer NIC bill.
As a quick example, an employee on a £35,000 salary pays £1,794.40 in Class 1 NICs over the year. Their employer pays £4,500 before any Employment Allowance.
What Are Class 1A National Insurance Contributions?
Class 1A National Insurance is an employer-only charge, set at 15% in 2026–27, on the taxable value of most benefits in kind.
Common benefits in kind that attract Class 1A include:
- Company cars
- Private medical insurance
- Interest-free or low-interest loans
- Gym memberships or other non-cash perks
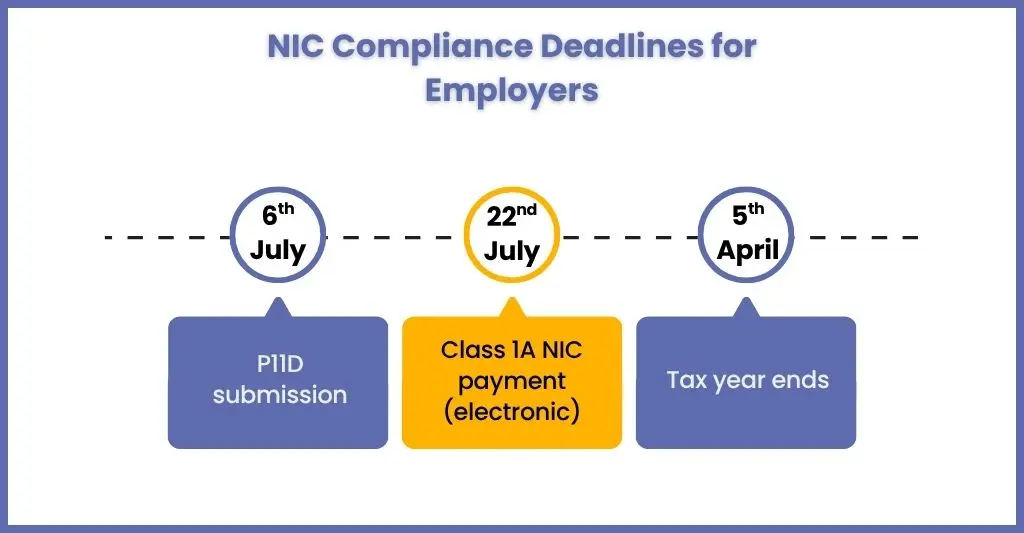
These contributions are paid at a flat percentage rate on the value of benefits and must be reported via P11D forms, usually due by 6 July following the tax year. The payment deadline for Class 1A NICs is 22 July (if paid electronically). Class 1A NICs are calculated annually and reported via Form P11D (to declare employee benefits) and Form P11D(b) (to report and calculate the Class 1A NICs due).
HMRC plans to make payrolling of most benefits in kind mandatory from 6 April 2027. For most benefits, Class 1A will then be reported and paid through payroll in real time instead of once a year.
What Are Class 2 National Insurance Contributions?
Class 2 National Insurance is a flat-rate weekly contribution for self-employed people, set at £3.65 a week in 2026–27. It protects entitlement to the State Pension and some benefits.
Since 6 April 2024, nobody has been required to pay Class 2. Self-employed clients with profits at or above the Small Profits Threshold of £7,105 are treated as having paid, so they still get a qualifying year. Clients with profits below £7,105 can pay voluntarily through Self Assessment to protect their record.
From 6 April 2026, voluntary Class 2 can no longer be paid for time spent abroad. Those clients now need Class 3, and new applicants must show 10 years of UK residence or contributions. Practices with heavy Self Assessment volumes often pass these record checks to a personal tax outsourcing team.
What Are Class 3 National Insurance Contributions?
Class 3 National Insurance Contributions are voluntary payments of £18.40 a week in 2026–27 (£956.80 for a full year) that fill gaps in a National Insurance record.
People make Class 3 NICs voluntarily to fill gaps in their National Insurance (NI) records. These contributions help ensure eligibility for certain state benefits, most notably the full State Pension. They can make voluntary contributions for the past 6 years, with the deadline on 5th April each year.
Unlike Class 1 or Class 2 NICs, Class 3 is not tied to employment or self-employment. Instead, it’s a way for people to maintain or boost their contribution record if they haven’t earned enough in a given year to qualify for a full contribution.
What Are Class 4 National Insurance Contributions?
Class 4 National Insurance Contributions are paid by self-employed people on their annual profits. In 2026–27 the rate is 6% on profits between £12,570 and £50,270 and 2% on profits above £50,270.
Class 4 is worked out and paid through the Self Assessment tax return, alongside Income Tax. It does not count towards the State Pension. That entitlement comes from Class 2.
How Do I Check My National Insurance Contributions?
You can check National Insurance Contributions by signing in to the HMRC Personal Tax Account or the HMRC app and opening the National Insurance record.
Taking a glance at the NICs is essential for understanding your client’s entitlement to State Pension and other UK benefits. Whether your client is employed, self-employed, or has gaps in their working history, by reviewing their NI record, you can ensure everything is up to date.
To check your client’s NICs, you can use the National Insurance record online method using HMRC’s digital services.
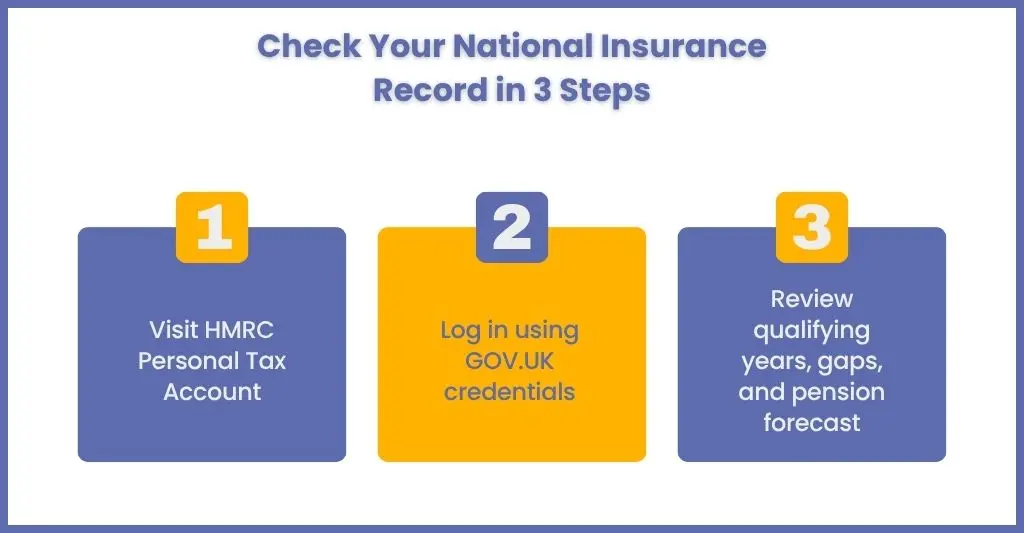
Here’s how you do it:
- Visit the HMRC National Insurance record page.
- Sign in to your Personal Tax Account
- View the records, where you will get to see the number of qualifying years on record, any gaps in contributions, whether you can make voluntary contributions (Class 3), and your current State Pension forecast
Why Do National Insurance Contributions Matter?
National Insurance Contributions matter because they decide whether someone qualifies for the State Pension and contributory benefits, and because errors leave employers open to HMRC interest and penalties.
National Insurance Contributions are not just a payroll deduction. It is a path for ensuring long-term financial security. Therefore, individuals, employers, and your team alike need to understand NICs clearly for sound financial planning and compliance.
The sums involved keep growing. ONS public sector finances data published in August 2026 puts NIC receipts at £65.6 billion for April to July 2026, which is 4.0% more than in the same four months of 2025.
NIC helps in the following matters:
Builds Entitlement to the State Pension
The NIC record of your client will determine whether it will qualify for the basic or new state pension. Your client will need 10 qualifying years to get any State Pension and 35 qualifying years to receive the full State Pension. Missing out on contributions or incomplete years can reduce your client’s retirement income, which is why accuracy and timely payments are a must.
Access to Essential State Benefits
You can gauge the importance of National Insurance Contributions (NICs) from the fact that many UK welfare benefits directly tie to your NIC record, including:
- Maternity Allowance
- Jobseeker’s Allowance
- Bereavement Support Payments
- Employment and Support Allowance (ESA)
By failing to contribute adequately, your client will be disqualified from these safety nets when they’re most needed.
Ensures Compliance for Employers
It’s a legal obligation for employers to pay accurate NICs because any inaccuracies will lead to cascading problems such as:
- HMRC penalties and interest
- Damaged employer reputation
- Payroll corrections and administrative headaches
Accounting firms play a vital role in ensuring their clients are fully compliant with the latest rates, NIC thresholds, and reporting duties. For further refinement in service quality, practices are utilising payroll outsourcing services provided by outsourcing partners. At Corient, an ACCA-trained payroll team handles NIC calculations and HMRC submissions for UK accountancy practices on BrightPay, Sage, Xero and QuickBooks, under ISO 27001 and Cyber Essentials certified controls.
Helps Individuals Fill Gaps in Employment
If your clients have been unemployed, on parental leave, ill, or living abroad, they can fill contribution gaps and protect their benefits by using voluntary NICs (Class 3). As an accounting practice, you can guide your clients to understand and act on these options to secure their future entitlements.
Financial Planning and Retirement Readiness
NICs affect how much clients will receive from the state in retirement, which impacts how much they need to save privately.
Enhancing the understanding of your client of NIC implications helps in:
- Guide pension planning
- Assess the value of topping up contributions
- Plan transitions to self-employment or part-time work
How Is National Insurance Paid in the UK?
National Insurance is paid through PAYE for employees and employers, through Self Assessment for the self-employed, and directly to HMRC for voluntary contributions.
NICs are paid in multiple ways based on your client’s employment status. Whether your clients are employed, self-employed, or making voluntary contributions, the process ensures regular, accurate payments into the UK’s welfare system.
Here’s how NICs are collected:
- Employees: Through PAYE payroll deductions.
- Employers: Must pay employer NICs and Class 1A via payroll systems and P11D forms. Monthly PAYE and NIC payments are due by the 22nd of the following tax month if paid electronically, or the 19th by post.
- Self-employed: Through the Self-Assessment tax return (Class 2 and Class 4).
- Voluntary contributors: Pay Class 3 via HMRC’s online portal or direct debit.
Make sure your payroll teams use the best payroll software which will automatically be updated with the latest rates and NIC thresholds each April.
What If You Overpay or Underpay National Insurance?
If National Insurance is overpaid, HMRC will refund it once a claim is made. If it is underpaid, the shortfall has to be paid and HMRC can add interest and penalties.
There can be an overpayment or underpayment of NICs. In that case, you can claim a refund. Such mistakes happen when your clients are changing jobs mid-year or have multiple jobs in hand.
You, on behalf of your client, can request a refund via HMRC and also review the annual NIC record for discrepancies. Additionally, you must pay attention to payroll miscalculations, late payments, and missed contributions, which cause underpayments. Penalties and interest may apply for late NICs. You can avoid this by conducting a mid-year or year-end payroll review for your clients.
What Has Changed for National Insurance Contributions in 2026?
From 6 April 2026, the Class 1 rates stayed the same, while the Class 2 rate, the Class 3 rate, the Lower Earnings Limit and the Small Profits Threshold all went up. The table compares the two tax years.
| Item | 2025–26 | 2026–27 |
| Employee Class 1 main rate | 8% | 8% (no change) |
| Employer Class 1 rate | 15% | 15% (no change) |
| Secondary Threshold | £5,000 a year | £5,000 a year (no change) |
| Lower Earnings Limit | £125 a week | £129 a week (£6,708 a year) |
| Class 2 weekly rate | £3.50 | £3.65 |
| Small Profits Threshold | £6,845 | £7,105 |
| Class 3 weekly rate | £17.75 | £18.40 |
Source: HMRC, Rates and allowances: National Insurance contributions, updated 6 April 2026.
Two later changes are worth putting in client diaries now. The main thresholds are frozen until April 2031. And from 6 April 2029, pension contributions made by salary sacrifice above £2,000 a year will attract both employee and employer Class 1 NICs.
What Are the National Insurance Rates and Thresholds for 2026–27?
For 2026–27 (6 April 2026 to 5 April 2027) the main National Insurance rates are 8% for employees, 15% for employers, 6% on self-employed profits, £3.65 a week for Class 2 and £18.40 a week for Class 3.
| NIC Class | Who Pays It | Rate | Threshold |
| Class 1 (Employee) | Employees | 8% up to £50,270, then 2% | £12,570/year |
| Class 1 (Employer) | Employers | 15% | £5,000/year |
| Class 1A | Employers | 15% | On value of benefits |
| Class 2 | Self-employed (Voluntary only) | £3.65/week | £7,105 Small Profits Threshold |
| Class 3 | Voluntary | £18.40/week | N/A |
| Class 4 | Self-employed | 6% up to £50,270, then 2% | £12,570/year |
Source: HMRC, Rates and thresholds for employers 2026 to 2027.
Frequently Asked Questions (FAQ)
1. How do I check my National Insurance Contributions on HMRC?
You can check a National Insurance record online through the HMRC Personal Tax Account or the HMRC app. The record lists the contributions for every tax year, shows any gaps, and says whether voluntary top-ups are allowed. Accountants generally cannot open this record themselves, so clients need to download it or share a screenshot with their adviser.
2. What is the difference between Class 1 and Class 1A National Insurance?
Class 1 National Insurance is charged on employee earnings. Both the employee (8%, then 2%) and the employer (15%) pay it through payroll every pay period. Class 1A is paid by the employer only, at 15% in 2026–27, on taxable benefits in kind such as company cars. It is settled once a year, by 22 July.
3. Is there a penalty for missing contributions or paying late?
Yes. HMRC charges interest on late National Insurance from the date it was due. Late PAYE payments can also bring penalties of 1% to 4% of the amount paid late, depending on how many times the employer defaults in the tax year. Amounts still unpaid after six and twelve months can each attract a further 5%. Regular payroll reviews help prevent this.
4. What can affect National Insurance Contributions?
The amount of National Insurance a client pays depends on employment status, earnings, age and National Insurance category letter. Employees stop paying at State Pension age. Employers pay 0% on earnings up to £50,270 for under-21s and for apprentices under 25. Directors are assessed over an annual earnings period, and holding more than one job can change the total.
5. What counts as a full year for NI contributions?
A qualifying year is a tax year (6 April to 5 April) in which someone pays, is treated as paying, or is credited with enough National Insurance. In 2026–27 an employee needs earnings of at least £6,708, which is the Lower Earnings Limit of £129 a week for 52 weeks. Ten qualifying years are needed for any new State Pension and 35 for the full amount.
Conclusion
It is essential to have a deeper understanding of National Insurance Contributions, which will enable you to guide your clients effectively. With changing rates, Class 2 now voluntary, and new compliance challenges, accounting practices in the UK must be proactive. Whether it’s advising on voluntary contributions, correcting overpayments, or ensuring accurate payroll deductions, your expertise can safeguard your clients’ financial future and ensure full compliance.
Furthermore, to enhance your understanding of NICs, consider consulting a professional service provider with considerable experience in handling these tasks, such as Corient. Through its payroll services, it has achieved the goal of relieving countless practices from the time-consuming NIC tasks. Corient has 14 years of outsourcing experience with UK accountancy firms, a team of 600+, and white-label delivery built for large and multi-partner practices. If you are interested in learning more about our services and achievements, you can use our contact form and connect with us.