A P11D reports an employee’s taxable benefits, such as a company car or private medical cover, to HMRC. The 2025/26 deadline was 6 July 2026; the 2026/27 forms are due 6 July 2027, with Class 1A NIC at 15% payable by 22 July 2027. Mandatory payrolling begins 6 April 2027 for some benefits.
Are you aware of a simple guide in place to answer the questions posed by your employer clients regarding P11D? Such a guide will be particularly convenient now, as we are in the midst of the 2026/27 tax year. You must have noticed that your UK client employers are already concerned about their increased obligations, and none is more critical than submitting the P11D form. These forms, which account for employee benefits and expenses, often become an unseen compliance risk for businesses.
A P11D form is used by UK employers to report benefits and expenses provided to employees, such as company cars or medical insurance. The guide prepared by us will make it easy for your clients to understand how to file P11D and P11D(b) forms for the current tax year, key deadlines, penalties, and how to stay compliant with HMRC. It is written for large practices that file P11Ds for many employer clients, and it has been updated for the 2026/27 cycle.
In this blog, we will explain everything you need to know with this P11D Guide for accurate and compliant reporting of employee benefits.
Key takeaways
- A P11D lists each employee’s taxable benefits. The P11D(b) is one return per employer that totals the Class 1A NIC due.
- For 2026/27 benefits, file and give employees their copies by 6 July 2027, then pay Class 1A NIC by 22 July 2027 (19 July by cheque).
- Class 1A NIC is 15% for 2025/26 and 2026/27, up from 13.8%.
- A late P11D(b) costs £100 per 50 employees for every month or part month.
- From 6 April 2027, payrolling is mandatory for company cars, car fuel, vans, van fuel and medical benefits. Most other benefits follow in April 2028. P11Ds are not gone yet.
What Is a P11D?
The P11D is a form used for reporting benefits provided by employers to their employees. This form must be completed for each employee who receives certain taxable benefits and expenses and must be submitted to HMRC on an annual basis.
The expenses that need mentioning in the P11D form are:
- Company car/fuel
- Company vans (provided for personal use)
- Private medical insurance
- Employer loans over £10,000 (where no/low interest charged)
- Professional/private memberships
- Accommodation
What Is a P11D(b)?
P11D(b) is a form that is submitted to the HMRC, and it shows the total value of benefits provided to an employee and Class 1A National Insurance Contributions (NIC) due on them. We have noticed that your clients get confused between P11D and P11D(b). You can make them understand that the P11D form details the specific benefits given to each employee. On the other hand, the P11D(b) summarises the overall employer liability for Class 1A National Insurance Contributions (NICs). Class 1A NIC is an employer-only charge on most taxable benefits. Employees do not pay it.
Who Needs to Submit a P11D and P11D(b)?
It is the responsibility of every UK-based employer to submit P11D for every employee who has received taxable benefits and has not been processed in payroll. Nowadays, due to work pressure, P11D filing and submission are often handled by accounting practices on behalf of their clients. If your clients provide benefits for the tax year, then P11D(b) is also required.
How Do You File a P11D in 2026? Step by Step
List the benefits, work out their taxable value, complete a P11D for each employee, file the P11D(b), give employees their copies, then pay Class 1A NIC.
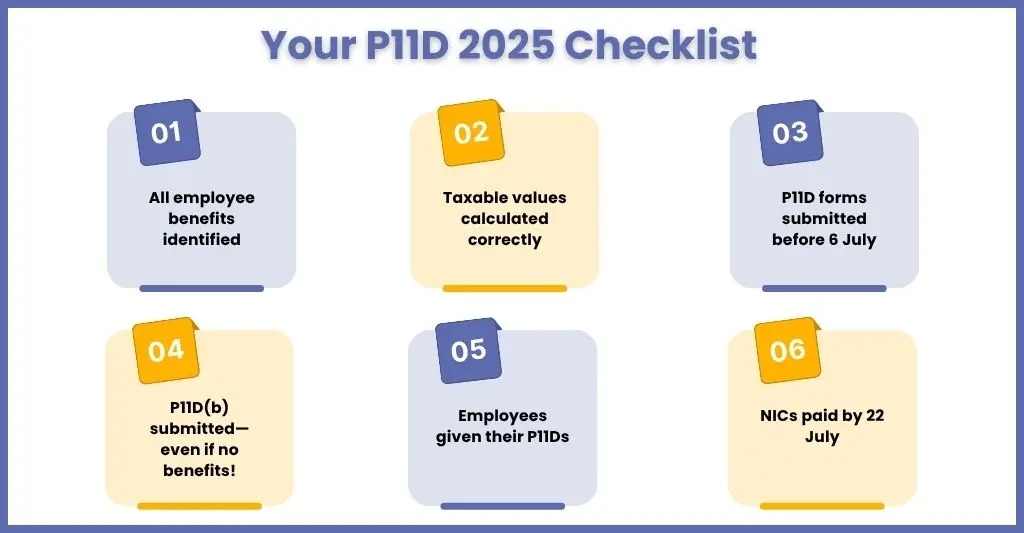
For your clients to understand P11D, they must understand the filing process. It is essential to note that preparing P11Ds is a complex and time-consuming process that involves collecting accurate data, calculating taxable values, and submitting them to HMRC. For the sake of simplification for your clients, we have broken it down into a few step-by-step processes. These steps are:
Identifying Benefits Provided
The first step is to identify all employees who are receiving benefits in addition to their salary for the current tax year. These benefits can range from one-time benefits, such as accommodation, to recurring ones, like fuel expenses. Maintain a detailed record of when benefits are issued and to whom.
Conduct Calculations of Taxable Value
Once the list of benefits is prepared, conduct the calculations on them to identify the taxable value of each. To do that, you will have to use the best payroll software that has built-in P11D functionality for ease of calculation. During calculations, follow HMRC guidance to apply correct valuation rules. Also, note that accuracy is critical here because incorrect values will lead to penalties and or additional NIC liabilities.
Fill out the P11D Form for Each Employee
For every employee who has received benefits outside their payroll, they must complete their P11D form. This form has to contain the following details:
- Employee’s name, NI number, and job title
- Type of benefit (e.g., company car, medical insurance)
- Value of the benefit
- Date the benefit started and ended, if applicable
Once the forms are completed, they must be submitted either through HMRC’s PAYE online system or using payroll software that supports P11D submission. It is worth remembering that if your client has not provided any benefits to their employees, then there is no need to submit P11Ds; however, they still need to file a P11D(b).
Prepare and Submit P11D(b) Form
P11D(b) is a summary form that contains the total value of all taxable benefits provided and Class 1A National Insurance Contributions due on those benefits. Even if your clients have paid all benefits, the P11D(b) must still be submitted to confirm NIC liability. The submission of the P11D (b) form can be done either through HMRC online services or payroll software integrated with HMRC. If there are no benefits to report, then P11D(b) must be submitted with a nil return.
Distribution of P11D Copies to Employees
By 6 July after the tax year ends (6 July 2027 for 2026/27 benefits), your clients will be legally required to provide each affected employee with a copy of their P11D form.
With the P11D copies in their hand, your client’s employees will be able to:
- Understand the benefits reported to HMRC
- Accurately complete their Self-Assessment (if applicable)
- You can provide the form to your client’s employees in either paper or secure digital format.
Pay Class 1A National Insurance Contributions (NICs)
Finally, calculate the Class 1A NICs based on the total value of benefits reported and pay it to HMRC.
- For the 2025/26 and 2026/27 tax years, the Class 1A NIC rate is 15% of the taxable benefit value, up from 13.8% (CIPP, June 2026).
- Payments can be made through HMRC’s online payment portal, via BACS, Faster Payments, or direct debit.
Deadlines:
- Electronic payments must reach HMRC by 22 July (22 July 2027 for 2026/27 benefits)
- Cheque payments must arrive by19 July (19 July 2027 for 2026/27 benefits)
What Is the P11D Deadline in 2026 and 2027?
Forms are due by 6 July after the tax year ends. The 2025/26 deadline was 6 July 2026 and has passed. For 2026/27 benefits, the deadline is 6 July 2027.
| Tax year of benefits | File P11D/P11D(b) and give employees copies | Pay Class 1A NIC online | Pay Class 1A NIC by cheque |
| 2025/26 | 6 July 2026 (passed) | 22 July 2026 | 19 July 2026 |
| 2026/27 | 6 July 2027 | 22 July 2027 | 19 July 2027 |
Dates confirmed by CIPP, June 2026, and Azets, 2026.
The P11D deadline for reporting employees’ benefits and submitting forms is 6 July each year. Additionally, a copy of these forms must be provided to the employees by July 6th. Also, it should be noted that the payment of Class 1A National Insurance (NICs) must be made by July 22nd (online).
P11D Penalties: What Happens If You Miss the Deadline?
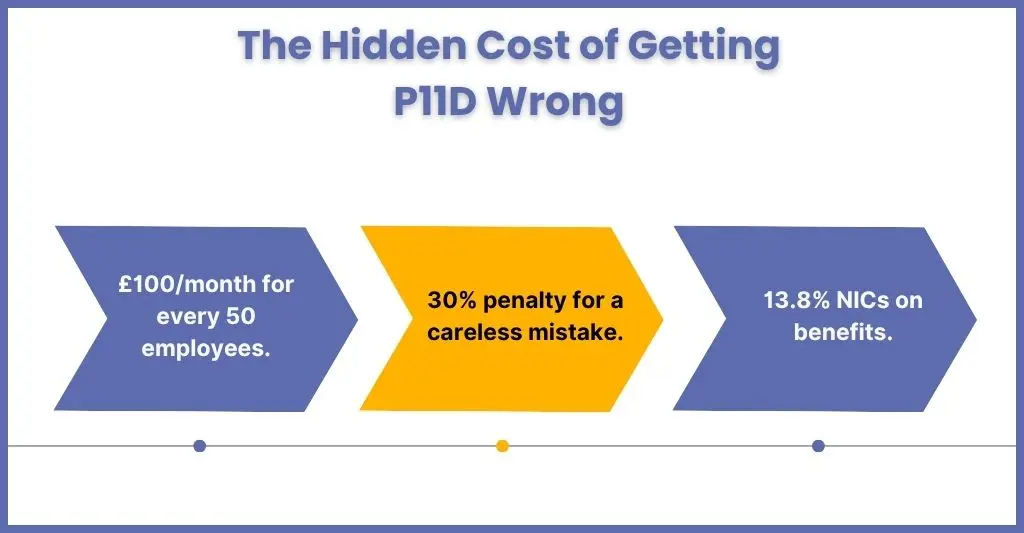
Missing the P11D or P11D(b) deadline can result in automatic penalties from HMRC even if you had no benefits to report. Penalties are applied based on the extent of the delay in submission and the number of employees affected.
Late Submission Penalties
In the case of late submissions, your clients will be subject to a £100 penalty per 50 employees for each month or part month the P11D(b) is late.
Incorrect Information
There is a range of penalties in place for incorrect information on P11D and P11D(b) forms. Starting from 100% of the potential lost tax for concealing information, 70% on deliberate but non-concealing information, and 30% on careless actions. An incorrect P11D can also cost up to £3,000 per form (Crowe UK, 2026).
Penalties on Late Payment
If Class 1A National Insurance Contributions are not paid by July 22nd 2025, HMRC may charge Interest or Surcharges for persistent delays
Are P11Ds Being Abolished From April 2027?
Partly. Mandatory payrolling starts on 6 April 2027 for five benefit types, with most other benefits following on 6 April 2028. P11Ds are still needed for 2025/26 and 2026/27 and for loans and living accommodation.
Payrolling means reporting the taxable value of a benefit through payroll each pay period, instead of on a P11D after the year ends. Class 1A NIC is then paid in real time too.
| When | What changes | P11D still needed? |
| Up to 5 April 2027 | All benefits not voluntarily payrolled are reported on P11D and P11D(b) | Yes |
| From 6 April 2027 (phase 1) | Company cars, car fuel, vans, van fuel and employer-provided medical benefits must be payrolled | No, for those benefits |
| From 6 April 2028 (phase 2) | Most other benefits in kind must be payrolled | No, for most benefits |
| Outside mandatory payrolling | Employment-related loans and living accommodation | Yes, for now |
Sources: ACCA, June 2026; Affinity Associates, October 2026.
Note that the 2026/27 Class 1A NIC is still paid by 22 July 2027 under the current P11D(b) process (Lewis Silkin, September 2026). For a large practice, 2027/28 means running payrolling and P11Ds side by side.
What Are the Most Common P11D Mistakes and How Do You Avoid Them?
The five most common errors are missing benefits, wrong valuations, late filing, wrong employee details and manual entry.
Even the most experienced employer or practice can make mistakes when preparing P11D. Here are some common mistakes and how to avoid them.
Missing Out on Reportable Benefits
Failing to report benefits that are taxable, such as company cars, private medical insurance, or interest-free loans, is a common mistake made by multiple clients and practices. To avoid it, you must have a detailed record of all the benefits given to employees throughout the year and conduct a check before submission.
Errors in Valuation of Benefits
Wrong calculations of benefits are a common occurrence when reporting benefits. However, by utilising the latest accounting software and adhering to the current year’s tax guidelines, you can rectify this mistake.
Late Submissions
Missing the 6th July submission deadline for P11D forms is a common mistake. However, by marking the date or by utilising a payroll service provider, you can easily overcome this problem.
Errors in Employee Information
You must have encountered the issue of incorrect employee information, such as employee names, National Insurance numbers, or benefit allocations, from your clients. Hence, double-check the information provided and use payroll software for further validations.
Manual Entry
Manual entries are an invitation to make errors. Hence, consider using accounting software or outsourcing P11D preparation to a specialist provider for accuracy and peace of mind.
You must have noticed that all these mistakes occur due to a lack of expertise or a failure to meet deadlines. Hence, you must get hold of an expert to get the P11D job done perfectly, which you will find from payroll service providers.
How Can Payroll Outsourcing Help You Stay P11D Compliant?
It gives your practice trained people, payroll software and a compliance calendar for P11D work. The employer still remains responsible to HMRC.
Gone are the days when businesses in the UK had the time to handle P11D forms by themselves; now, this critical but time-consuming responsibility is dealt with on their behalf by accounting practices.
However, practices are now facing a situation of increased complexity and workload, which is hampering their productivity and accuracy. For this reason, many practices are opting for payroll outsourcing services and entrusting their P11D responsibilities to experts.
Here is how payroll outsourcing services of a professional service provider will help your client stay compliant.
Automated Benefit Reporting to Ensure Nothing Is Missed
Professional outsourcing providers will utilise the latest and most advanced payroll software, which automatically identifies and tracks employee benefits throughout the year. Such automation will ensure that no taxable benefit, such as a medical policy or company car, is left out. Thanks to automated reporting, there will be no manual interventions during last-minute rushes.
Real-Time Compliance Tracking
UK tax regulations are constantly changing, particularly about benefit-in-kind rules and National Insurance Contributions. Professional outsourcing providers closely monitor the latest HMRC updates and implement them across their systems to ensure compliance with no issues. For instance, when the April 2027 payrolling rules start, an outsourced team can set up cars, fuel, vans and medical benefits for every client payroll in one go.
Dedicated Payroll Experts to Handle P11Ds End-to-End
The best payroll outsourcing company will have a team of trained experts who are experienced in handling the P11D process, right from data collection and calculation to filing and employee communication. Such a team will ensure accuracy and less burden on your clients and your practice. When an expert is by your side, you will not have to worry about heavy lifting. At Corient, our payroll team in Coventry is led by Rupesh Nagvekar, who has 13 years in accounting and finance, and we use AI tools such as Sherlock for error detection to catch mistakes before filing. See our payroll outsourcing service for how it works.
Distribution of P11D to Employees
A reputable provider doesn’t just file with HMRC they also ensure that each employee receives their P11D form by the legal deadline (6 July) in either paper or secure digital format. This reduces follow-up queries and supports employee tax self-assessments.
Timely Reminders and Compliance Calendars
Outsourced services often provide automated reminders to practices for critical dates, such as:
- P11D and P11D(b) submission deadlines
- Class 1A NIC payment due dates
- Monthly benefit reconciliation checks
This means you’re never caught off-guard, even during peak periods like year-end.
Frequently Asked Questions About the P11D Guide
1. What is a P11D form used for?
A P11D reports the taxable benefits and expenses an employer gives a director or employee, such as company cars, vans, private medical insurance, living accommodation and low-interest loans over £10,000. HMRC uses it to calculate the employee’s income tax through their tax code, while the employer’s Class 1A NIC is reported separately on the P11D(b).
2. What is the P11D deadline?
P11D and P11D(b) forms are due with HMRC by 6 July after the tax year ends on 5 April, and employees must receive their copy by the same date. For 2025/26 that was 6 July 2026. For 2026/27 it is 6 July 2027. Class 1A NIC is payable by 22 July, or 19 July by cheque.
3. Can I correct a P11D after submission?
Yes. Complete a new P11D marked as a replacement and send it the same way as the original, through HMRC’s PAYE online service or compatible payroll software. Give the employee a corrected copy too. Correct errors quickly, because an incorrect P11D can attract a penalty of up to £3,000 per form, and a changed P11D(b) may alter the Class 1A NIC due.
4. Are P11D being phased out?
Partly. From 6 April 2027, payrolling becomes mandatory for company cars, car fuel, vans, van fuel and employer-provided medical benefits, with most other benefits following on 6 April 2028. Loans and living accommodation stay on the P11D for now. P11Ds are still needed for 2025/26 and 2026/27, so keep the process running.
5. Can you submit a P11D without a PAYE scheme?
No. A PAYE scheme is needed to file a P11D, so a client that provides benefits must register as an employer with HMRC first. Register early, because filing late attracts penalties of £100 per 50 employees for each month or part month the P11D(b) is outstanding.
6. What is the Class 1A NIC rate?
Class 1A NIC is an employer-only charge on most taxable benefits. The rate is 15% for both 2025/26 and 2026/27, up from 13.8% in earlier years. For example, £6,800 of taxable benefits creates £1,020 of Class 1A NIC. It is declared on the P11D(b) and paid by 22 July after the tax year.
Wrapping Up
Armed with this guide, you will be better equipped to educate your clients about the workings of P11D. With your clients being aware of the deadlines and penalties, you can expect a reduction in errors and an increase in productivity, which will benefit both you and your clients.
Understandably, filing and submitting a P11D can be a daunting task, considering the complexities and volume involved. However, with the proper knowledge, tools, and support, such as outsourcing payroll, you can help your clients stay compliant, avoid penalties, and ensure their employees’ benefits are reported accurately. Corient can help you achieve this.
Since 2011, we have been helping multiple accounting practices streamline their payroll processing, including P11D filing and submission. If your practice or business wants stress-free P11D filing with zero penalties, Corient is ready to help. Talk to our payroll experts today to stay ahead of deadlines and HMRC. Write to us using our website contact form, and our executive will get in touch with you. You can also check our payroll pricing or read about our tax outsourcing support.