UK GAAP changes mean FRS 102 now applies a five-step revenue model based on IFRS 15 and an on-balance-sheet lease model based on IFRS 16 for accounting periods beginning on or after 1 January 2026. Large practices must update daily bookkeeping, policies and documentation, not just year-end accounts, to stay audit-ready.
UK GAAP changes in 2026: Are you really ready for them? For many practices, the honest answer is not yet. While it’s good that you are aware of the changes to UK GAAP, that’s not enough; you need to invest in updating your workflows, systems, and bookkeeping processes to handle them effectively.
Let’s understand this through an illustrative scenario.
A UK-based accounting practice has already done accurate year-end accounts under Financial Reporting Standards 102 (FRS 102). But during the recent audit, the practice came face to face with unexpected queries around revenue recognition and lease accounting, areas impacted by the new UK GAAP changes.
This issue was created because the day-to-day bookkeeping workflows had not been updated as per the new requirements.
The result of it was:
- Delayed audit completion
- Additional rework
- Increased client pressure
The goal of the updates by the Financial Reporting Council (FRC) of FRS 102 is to align UK GAAP more closely with IFRS 15 and IFRS 16, with simplifications for UK entities. But it has also introduced a new complexity for accounting practices and their clients.
It’s not enough to understand the rules; you need to ensure your entire workflow is audit-ready.
Key Takeaways
- The FRC issued the FRS 102 Periodic Review 2024 amendments on 27 March 2024; most apply to accounting periods beginning on or after 1 January 2026 (FRC).
- Revenue now follows a five-step model based on IFRS 15 (FRS 102 and FRS 105), and most leases go on the balance sheet under an IFRS 16-based model (FRS 102) (ACCA).
- Early application required all amendments to be applied together; from 1 January 2026 they are mandatory (ICAEW).
- In a January 2025 IRIS survey of 500 in-house accountants, 24% were unaware of the FRS 102 lease changes and only 3% had completed adoption (IRIS).
- The changes affect daily bookkeeping, not only year-end accounts. Corient supports UK accountancy firms with bookkeeping, year-end and audit support, backed by AI tools such as Sherlock for error detection.
What Are the Latest Changes to UK GAAP?
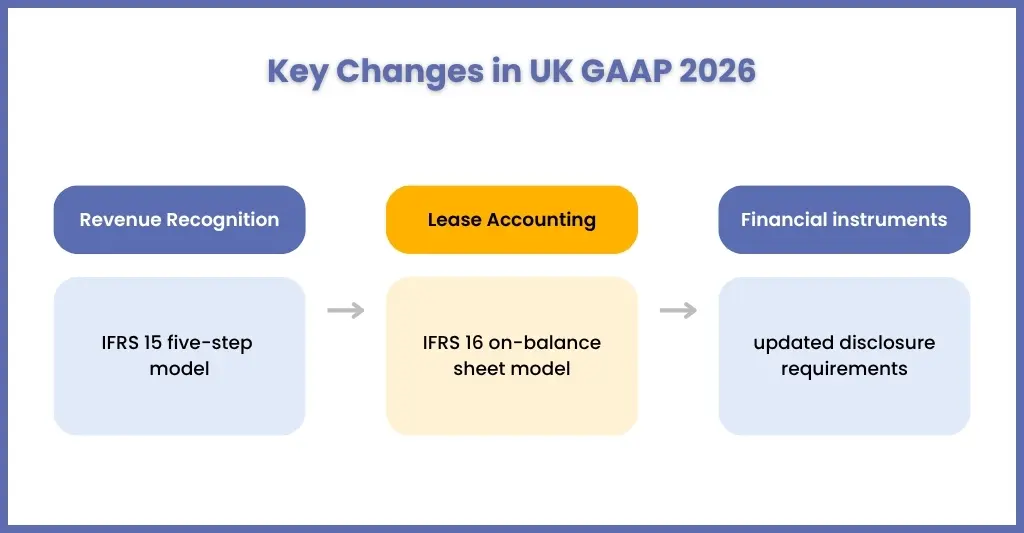
The latest UK GAAP changes are the FRC’s Periodic Review 2024 amendments to FRS 102. They introduce an IFRS 15-based revenue model and an IFRS 16-based lease model, and apply to accounting periods beginning on or after 1 January 2026. UK GAAP is the framework of accounting standards and law UK entities use to prepare financial statements, including FRS 101, FRS 102 and FRS 105.
FRS 102 is a single financial reporting standard that applies to the financial statements of UK entities that are not applying IFRS as adopted by the UK. The latest changes to the UK GAAP, especially to the FRS 102, apply to accounting periods beginning on or after 1 January 2026, for more transparency and closer alignment with IFRS.
It is important to note that these changes are going to have a significant impact on financial statements, which are:
- The revised revenue accounting requirements in FRS 102 and FRS 105 for revenue recognition are based on the IFRS 15 five-step model.
- Updated lease accounting requirements in FRS 102 as per the IFRS 16′ on-balance sheet’ model for simplification, bringing in more leases brought onto the balance sheet.
These changes affect more than year-end accounts: they change the way transactions are recorded throughout the year.
UK GAAP changes at a glance (FRS 102 Periodic Review 2024)
| Area | What changes | Applies to |
| Revenue (Section 23) | Five-step model based on IFRS 15; revenue is recognised when or as a performance obligation is satisfied | FRS 102 and FRS 105 |
| Leases (Section 20) | Lessees recognise most leases on the balance sheet as a right-of-use asset and lease liability; exemptions remain for short-term (under 12 months) and low-value leases | FRS 102 |
| Fair value (new Section 2A) | New section aligned with IFRS 13 | FRS 102 |
| Supplier finance | New disclosures apply earlier, from periods beginning on or after 1 January 2025 | FRS 102 |
| Transition (leases) | Modified retrospective approach; comparatives are not restated | FRS 102 |
Sources: FRC FRS 102 explainer, June 2026; ACCA; Moore UK; IAS Plus.
Key dates
| Date | Milestone |
| 27 March 2024 | FRC issues the Periodic Review 2024 amendments to FRS 102 and other FRSs |
| 1 January 2025 | Earlier effective date for supplier finance arrangement disclosures |
| 1 January 2026 | Main effective date: accounting periods beginning on or after this date |
| Start of first period applied | Date of initial application, for example 1 January 2026 for a December year-end |
Sources: FRC; ICAEW helpsheet. Early application was permitted only if all amendments were applied at the same time.
How Do the UK GAAP Changes Affect Your Financial Reporting?
They change how revenue is recorded, how leases are treated and how financial data is structured, all through the year rather than only at year-end. Practices that wait for the audit risk rework, longer audits and higher compliance risk.
When it came to these changes in UK GAAP, we have come across many accounting practices telling us, “We’ll deal with this at year-end”. But that’s a risky thing to do.
Why?
Because these changes will affect:
- In what way is revenue recorded
- How leases are treated
- How financial data is structured
Awareness is still a gap. In a January 2025 survey of 500 in-house accountants, IRIS found that 24% were unaware of the FRS 102 lease changes, only 3% had completed adoption and 54% planned to buy lease accounting software (IRIS/Censuswide, 22–27 January 2025). Many are at risk of non-compliance.
If your bookkeeping services and your clients are not aligned with the latest changes, then you will face:
- Multiple reworks in the financial statements you prepared
- Longer audits
- Increase in compliance risk
Practices that incorporate the changes in UK GAAP the earliest will be less likely to stress during audits, which avoids extra costs and delays.
What Are the Common Pitfalls for Accounting Teams Under the New UK GAAP?
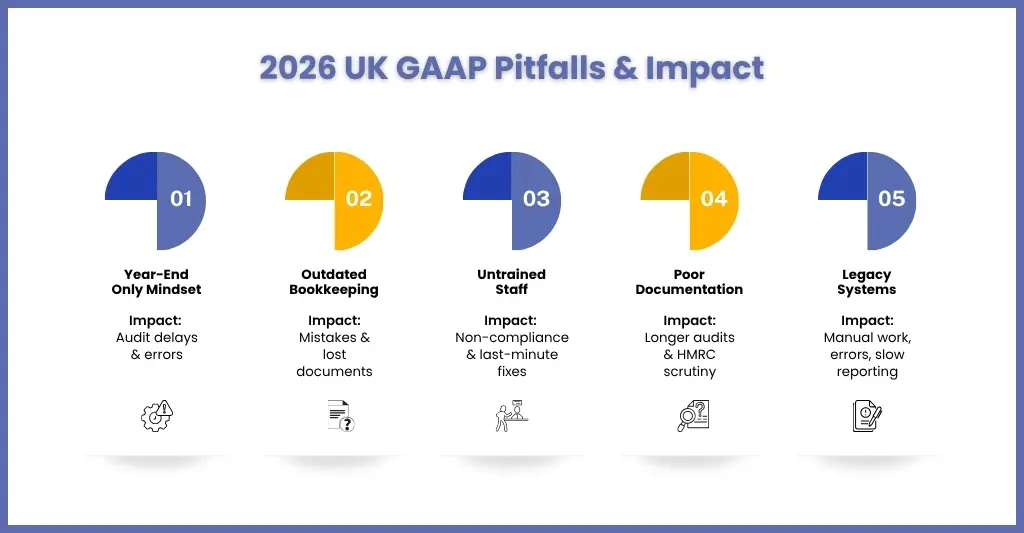
The most common pitfalls are treating the changes as year-end only, outdated bookkeeping, untrained staff, weak documentation and legacy systems. Each one is a workflow problem, not a technical-knowledge problem.
Understanding the new UK GAAP changes is more than just reading them. We have often encountered accounting teams struggling with it, not due to a lack of technical knowledge, but because their workflows, processes, and systems have not evolved as per present compliance requirements. Let’s understand these pitfalls.
Treating Changes as Year-End Only
One of the biggest mistakes firms make is assuming that UK GAAP changes are relevant only at the year-end audit.
In reality, these new rules around revenue recognition,and lease accounting impact the daily bookkeeping entries and transactions.
Impact:
In case these adjustments are not incorporated right at the beginning, then your accountants will have to face multiple corrections at the year-end, leading to:
- Delay audit completion
- Surge the risk of errors
- Auditor queries
Compliance with new UK GAAP is a continuous responsibility. You must integrate these updated standards into daily workflows to avoid last-minute chaos.
Outdated Bookkeeping Processes
Are you still relying on manual processes, spreadsheets, or inconsistent categorisation? There was a time these used to work, but not anymore, especially under the new reporting standards.
- Hand-typed entries and paper records increase the possibility of errors.
- Different accountants may classify similar transactions differently, leading to audit discrepancies.
- Loss of receipts, incomplete documentation, or unverified journal entries will compromise audit integrity.
Impact:
Such outdated bookkeeping processes will create red flags for auditors. Even small errors in classification will lead to significant challenges, especially with new disclosure requirements.
The best way to avoid this mistake is to transform your bookkeeping by adopting cloud-based accounting solutions or avail bookkeeping outsourcing from professional providers like Corient.
Lack of Staff Training
Depending on software updates is not enough; you will need to train your accounting staff to reduce their knowledge gap when it comes to these new standards.
- New Revenue Recognition Rules: Your staff must know how to allocate revenue over multiple performance obligations rather than at a single point.
- Lease Accounting Changes: Accountants must correctly identify which leases fall on the balance sheet and which qualify for the short-term or low-value exemptions, calculate right-of-use assets, and adjust depreciation.
- Disclosure Requirements: Your teams must know how to prepare financial notes that satisfy auditors.
Impact:
Without proper training, even the best bookkeeping practices can result in:
- Errors in financial statements
- Non-compliance with FRS 102
- Hurried last-minute corrections that increase your workload and compliance risk
To negate this, you will need to conduct quarterly internal training schedules for your staff, or an even better way is to use the services of a professional outsourcing provider like Corient. They will effectively guide your staff in the application of new standards correctly in day-to-day workflows.
Poor Documentation
Apart from accurate numbers, an auditor will also demand evidence to back them, and that’s only possible through proper documentation of transactions.
These documents contain:
- Audit Trails: Each transaction or adjustment must be traced from the source document to the final report.
- Detailed Explanations: Narrative notes should explain assumptions, valuation methods, and accounting judgments.
- Consistent Records: Discrepancies across spreadsheets, ledgers, or software modules can delay audits and trigger queries.
The impact of poor documentation will lead to:
- More audit time and fees
- Delayed client reporting
- Reputational risk for your practice if auditors or regulators flag incomplete or inconsistent records
To avoid this, you must invest in a centralised document management system that stores all the source files, approvals, and commentary linked directly to financial transactions. Providers like Corient can help you in integrating documentation workflows into daily accounting tasks to ensure audit readiness.
Over-Reliance on Legacy Systems
We have noticed multiple practices still relying on outdated accounting software that are not designed for handling 2026 UK GAAP updates.
Older software may not support:
- New revenue recognition formats
- Lease accounting calculations
- Expanded disclosure templates
This will lead to manual workarounds, leading to inconsistencies and duplicate efforts across teams.
The impact of this will be:
- Slow down reporting
- Increase in errors due to manual adjustments
- Making compliance with FRS 102 and MTD integration cumbersome
The solution is to invest in cloud-based, GAAP-compliant accounting software that integrates:
- Real-time reporting
- Automated checks for FRS 102 adjustments
- Multi-user access for accountants, auditors, and clients
How Do You Prepare for the 2026 UK GAAP Changes? A Step-by-Step Guide
Prepare in five steps: assess current workflows, update accounting policies, train your team, upgrade technology and run regular reviews. Start with the workflow map, because it shows where revenue and lease data are currently missing.
Knowing the 2026 UK GAAP changes is not enough; you need to integrate them into every step of your accounting workflow. This is where many accounting practices falter by waiting till the year-end to adjust, and by the time they realise it’s too late.
To avoid such a situation for your practice, we have developed a step-by-step guide to stay compliant, reduce errors, and be audit-ready.
Step 1: Assess Current Workflows
Understand where your current processes stand right now by doing the following.
- Review Bookkeeping Processes
Conduct a detailed review of your bookkeeping processes by examining how transactions are currently recorded and identifying gaps that could create errors under the new standards.
- Recognise Gaps in Data Capture
Under the new UK GAAP changes, updated revenue recognition and lease accounting rules require more detailed information, so ensure all the important information is captured.
- Check Compliance with New Standards
Compare your current workflow against FRS 102 updates to identify areas of non-compliance.
Create a workflow map for each client type to identify compliance gaps. Using the audit outsourcing services of service providers, you can identify gaps quickly and take remedial measures. Corient’s audit services team can support this review.
Step 2: Update Accounting Policies
Perform updates in your accounting policies so they fulfil the new UK GAAP requirements. To do that, you will need to:
- Revise Revenue Recognition Policies
The new revenue accounting requirements are aligned with IFRS 15, it means revenue must be recognised over performance obligations rather than at a single point. Updates in your internal guidelines must be carried out accordingly.
- Update Lease Accounting Methods
As per the new rules, certain leases now come onto the balance sheet. This will change how right-of-use assets and lease liabilities are recorded. Leases are transitioned on a modified retrospective basis, and comparatives are not restated (FRC).
- Align with FRS 102 Changes
Ensure that financial statement templates, journal entries, and disclosures meet the updated standard.
Make sure your accounting staff is aware of these policies, and for a smooth integration, you will take the help of outsourcing service providers that offer standardised policy templates.
Step 3: Train Your Team
Even after creating the best process, it will fail if your accountants are not trained or aware of it. So, invest in:
- Teaching Your Staff About UK GAAP Updates
The updates, like revenue recognition and lease accounting, are new for your accountants, and they must be taught because they affect daily bookkeeping and reporting.
- Explain the Operational Impact
Make your accountants understand the impact of these changes in day-to-day entries, client reporting, and audit readiness.
- Emphasise Documentation Requirements
Focus on maintaining clear and consistent records for auditors and regulators.
Conduct short training sessions for your accountants. Also, practices that use Corient’s services often combine software automation with expert guidance, reducing training overhead while ensuring staff are fully compliant.
Step 4: Upgrade Technology
Old accounting software, legacy systems and manual spreadsheets are not designed to handle the complexity of the new rules. Therefore, you will need to invest in:
- Automated Categorisation
Systems that automatically categorise transactions reduce errors in revenue recognition and lease accounting.
- Real-time Reporting
Cloud-based solutions allow you to track changes throughout the year, ensuring your books are always audit-ready.
- Audit Trails
All transactions, adjustments, and journal entries must be traceable for compliance and verification.
This ensures automation isn’t just a convenience; it ensures compliance is embedded into your process. Corient combines its accounting team with AI tools, including Corby for reconciliation and Sherlock for error detection, to keep records consistent between reviews.
Step 5: Perform Regular Reviews
Don’t wait until the year-end to check compliance; conduct frequent checks. This can be done through
- Quarterly Reviews
Conduct an audit of a sample of transactions every quarter to see its compliance with updated FRS 102 standards.
- Error Tracking
Find discrepancies in the early stage to avoid year-end corrections.
- Client-Specific Adjustments
Some of your clients may have unique transactions that require greater attention, such as multi-property portfolios or foreign assets.
Incorporate automated compliance checks along with manual reviews.
What Do the UK GAAP Changes Look Like in Practice? Illustrative Examples
Two errors recur: recognising revenue upfront when it should be recognised over time, and leaving leases off the balance sheet. Both lead to audit adjustments, restated statements or delays. The examples below are illustrative, not named client cases.
Example 1: Revenue Recognition
A firm incorrectly recognised revenue upfront instead of over time.
Result:
- Audit adjustments required
- Financial statements restated
Example 2: Lease Accounting
Leases are not recorded on the balance sheet under the new rules.
Result:
- Non-compliance
- Audit delays
Why Might Your Bookkeeping Workflow Fail a 2026 FRS 102 Audit?
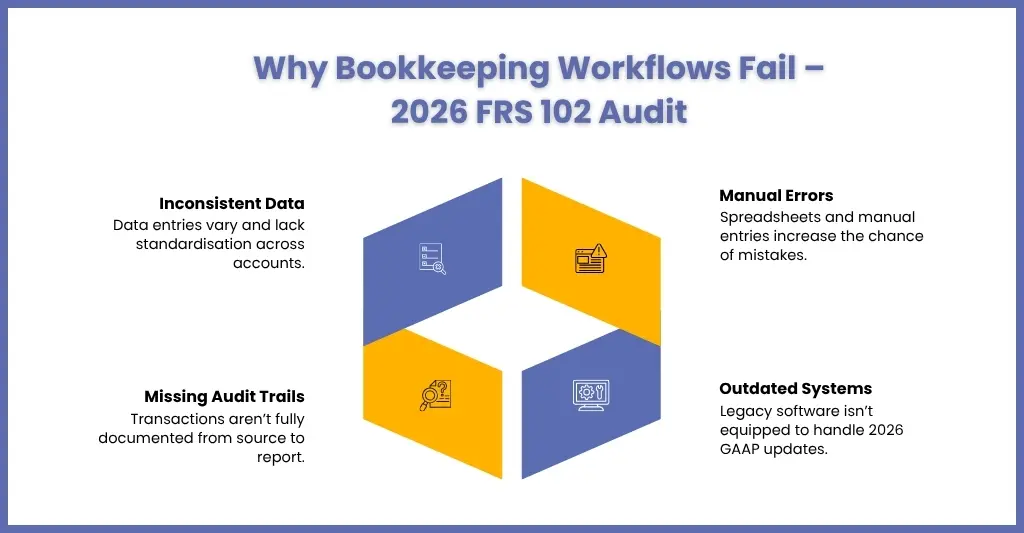
Workflows fail audits because of inconsistent data, missing audit trails and manual errors. Auditors need every transaction, adjustment and journal traceable and consistently categorised, which spreadsheets and legacy systems rarely deliver.
There are multiple reasons that can contribute to your bookkeeping workflow failure during a 2026 FRS 102 audit. Let’s become aware of those reasons so that effective action can be taken to negate them.
Inconsistent Data
With the implementation of the 2026 UK GAAP changes, you cannot ignore the lack of proper data management. 2026 UK GAAP updates require accurate data all the time, to avoid different categorisation methods or a lack of standardisation.
Follow a standardised template for categorisation of data.
Missing Audit Trails
Lack of documentation of transactions right from their source will lead to the loss of audit trails. This will cause problems during audits because auditors would like all your transactions, adjustments, and journal entries to be traceable and meet compliance.
Manual Errors
Avoid using manual spreadsheets to avoid errors like incorrect entries and missed adjustments. Even old accounting software and legacy systems are not designed to handle the complexity of the new rules, leading to manual intervention. Hence, focus on getting new accounting software and systems or explore the outsourcing option.
Most of these issues don’t show up until audit, and fixing them is costly and time-consuming, and this is where practices suffer the most. Therefore, to balance the workload and compliance, it is wise to choose outsourcing services to get the job done. Corient’s year-end accounts and bookkeeping teams work with UK accountancy firms to keep records audit-ready throughout the year.
Frequently Asked Questions (FAQ)
What are the key UK GAAP changes practices need to know in 2026?
The main changes are a new five-step revenue model in FRS 102 and FRS 105 based on IFRS 15, an on-balance-sheet lease model for lessees in FRS 102 based on IFRS 16, and a new fair value section. They also bring expanded disclosures, so bookkeeping and reporting processes both need updating.
Is early adoption of the new UK GAAP changes permitted?
Yes, early application was permitted, but only if all the Periodic Review 2024 amendments are applied at the same time. You cannot pick individual changes. For accounting periods beginning on or after 1 January 2026, the amendments are now mandatory, so any remaining decision is about transition, not timing.
How should firms update bookkeeping workflows to prepare for an audit?
Standardise how transactions are categorised, automate data capture, and keep a clear audit trail from source document to final report. Add quarterly sample reviews against the updated FRS 102 requirements, and record lease and revenue judgements in writing so auditors can follow your reasoning without rework.
When did the FRS 102 changes become mandatory?
The FRC issued the FRS 102 Periodic Review 2024 amendments on 27 March 2024. Most are mandatory for accounting periods beginning on or after 1 January 2026. A December year-end company therefore applies them for the year ending 31 December 2026, and its date of initial application is 1 January 2026.
What is the date of initial application under the new FRS 102?
The date of initial application is the start of the reporting period in which an entity first applies the amendments. For a company with a December year-end that does not adopt early, this is 1 January 2026, and opening balances for leases and revenue must be assessed from that date.
Do the lease changes require comparatives to be restated?
No. For leases, FRS 102 requires a modified retrospective approach: the cumulative effect of first applying the amendments is recognised as an adjustment to equity at the date of initial application, and comparatives are not restated. They continue to reflect the previous lease accounting, so clear disclosure matters.
Are You Ready for the 2026 UK GAAP Changes? Next Steps
Not until your day-to-day workflows, policies and documentation reflect the new revenue and lease rules. Start by mapping current workflows, then fix the gaps before the next audit cycle.
The UK GAAP changes in 2026 are not routine technical changes, but they require changes in your bookkeeping process, which increases your workload and compliance requirements.
For accounting practices, this means:
- Updating workflows
- Improving documentation
- Adopting better systems
Without preparation:
- Audits become difficult
- Errors increase
- Compliance risks grow
With the right approach and support from Corient, you can:
- Ensure audit-ready workflows
- Reduce manual effort
- Stay compliant with FRS 102
- Scale your practice confidently
Corient is a UK-focused outsourcing partner for accountancy firms, combining people and AI across bookkeeping, year-end accounts, audit support and tax. Our Director of Operations and New Business, Sachin Lohade, has 19+ years of experience with firms including BDO International, PricewaterhouseCoopers and Serco.
Have you still not updated your bookkeeping process as per 2026 UK GAAP? Not to worry, get connected with us through our contact form or book a 15-minute call, and we will ensure your compliance burden is taken care of.